
Both positions buy a call and a put to benefit from a sufficiently large move. A straddle shares one strike; a strangle separates the put and call strikes. Lower strangle premiums come with a wider region where neither option has intrinsic value at expiration.
What Are You Choosing Between?
Compare the move needed to recover the whole premium, not just the cost of each option. A trader expecting a very large move may accept the strangle’s farther strikes. A straddle responds to moves around its shared strike, but starts with more premium to recover.
The Main Differences
Swipe the table to compare all columns →
| Compare | Long Straddle | Long Strangle |
|---|---|---|
| Construction | Buy a call and put at the same strike. | Buy a lower-strike put and higher-strike call. |
| Example entry | $1,000 net debit | $600 net debit |
| Maximum profit | Unlimited | Unlimited |
| Maximum loss | $1,000 | $600 |
| Breakeven price | $90; $110 | $89; $111 |
A Practical Example
The $100 straddle costs $1,000. The $95/$105 strangle costs $600. At expiration their breakevens are $90/$110 and $89/$111 respectively. In these quotes the cheaper strangle still needs a slightly larger move to become profitable. A stock finishing at $100 loses the full debit in both positions.
XYZ is at $100 when the option trades are entered. Premiums below are per share; each option contract covers 100 shares. Each column shows one complete position, not an equal-capital allocation. Prices are hypothetical and exclude commissions, taxes, dividends, financing costs and early-assignment cashflows.
| Position | Example legs |
|---|---|
| Long Straddle | Buy 1 $100 call, 30 days, at $5 Buy 1 $100 put, 30 days, at $5 |
| Long Strangle | Buy 1 $95 put, 30 days, at $3 Buy 1 $105 call, 30 days, at $3 |
Comparing the Expiration Payoffs
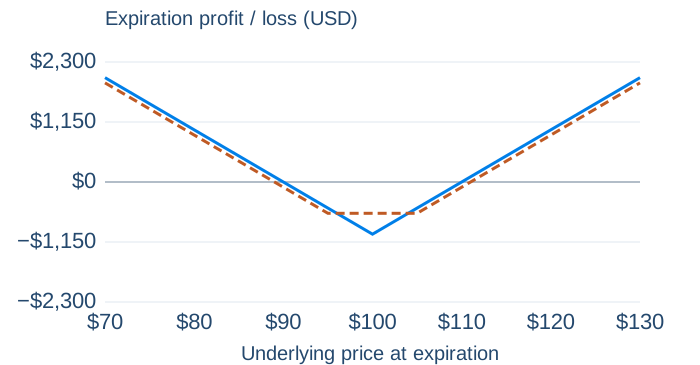
- Long Straddle
- Long Strangle
Swipe the table to compare all columns →
| XYZ price | Long Straddle | Long Strangle |
|---|---|---|
| $80 | $1,000 | $900 |
| $95 | −$500 | −$600 |
| $100 | −$1,000 | −$600 |
| $105 | −$500 | −$600 |
| $120 | $1,000 | $900 |
What to Watch For
A large earnings move is not enough if the price paid for volatility was too high. Before expiration, a fall in implied volatility can offset a favorable stock move. The expiration table excludes this interim repricing.
Before expiration, time value and implied volatility can change a position’s market value. Short options also create exercise and assignment obligations. Review the full strategy guides for position management and settlement details.
Explore the Strategies
Try the examples: