
A Bull Call Spread can use less opening capital than a Covered Call because a purchased call replaces the shares. The short call caps the upside in both examples. The lower capital requirement changes the downside and leverage; it does not make the spread universally superior.
What Are You Choosing Between?
Compare the amount that can be lost, whether stock ownership matters and how long the position can be held. Shares do not expire, but a call does. A shareholder may want dividends or continued ownership; a trader using a spread may want a defined option debit at risk and a specific expiration target.
The Main Differences
Swipe the table to compare all columns →
| Compare | Bull Call Spread | Covered Call |
|---|---|---|
| Construction | Replace the shares with a lower-strike call in the same expiration. | Own 100 shares and sell one call against them. |
| Example entry | $950 net debit | $9,700 net debit |
| Maximum profit | $550 | $800 |
| Maximum loss | $950 | $9,700 |
| Breakeven price | $99.50 | $97 |
Entry amounts include the stated stock purchase cost or short-sale proceeds. A net credit is not the broker’s required collateral, and historical stock cost is not new cash invested today.
A Practical Example
With stock at $100, the spread buys the $90 call for $12.50 and sells the $105 call for $3, costing $950. The Covered Call buys 100 shares and sells the same $105 call, costing $9,700 net. Both stop gaining above $105. Below $90, the spread’s loss stops at its debit, while the stock position keeps losing down to a zero stock price.
XYZ is at $100 when the option trades are entered. Premiums below are per share; each option contract covers 100 shares. Each column shows one complete position, not an equal-capital allocation. Prices are hypothetical and exclude commissions, taxes, dividends, financing costs and early-assignment cashflows.
| Position | Example legs |
|---|---|
| Bull Call Spread | Buy 1 $90 call, 30 days, at $12.50 Sell 1 $105 call, 30 days, at $3 |
| Covered Call | Own 100 shares at $100 Sell 1 $105 call, 30 days, at $3 |
Comparing the Expiration Payoffs
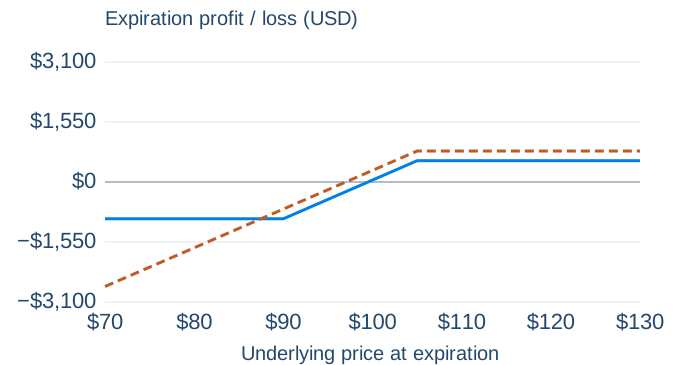
- Bull Call Spread
- Covered Call
Swipe the table to compare all columns →
| XYZ price | Bull Call Spread | Covered Call |
|---|---|---|
| $80 | −$950 | −$1,700 |
| $95 | −$450 | −$200 |
| $100 | $50 | $300 |
| $105 | $550 | $800 |
| $120 | $550 | $800 |
What to Watch For
The Covered Call’s loss is substantial but finite: $9,700 in this example if the stock reaches zero. A spread can lose 100% of its smaller debit. Comparing return percentages without also comparing dollar exposure, expiration and ownership can therefore be misleading.
Before expiration, time value and implied volatility can change a position’s market value. Short options also create exercise and assignment obligations. Review the full strategy guides for position management and settlement details.
Explore the Strategies
Try the examples: